PolyPid Reports Q1 2025 Results and Approaches Pivotal Data Readout: SHIELD II Results Could Transform Surgical Infection Prevention
 Sponsored · Market Discovery Content
PolyPid Ltd. (NASDAQ: PYPD)* released its Q1 2025 financial results on May 14, reaffirming that the company is on track for a potentially transformative milestone with top-line results from its Phase 3 SHIELD II trial expected by the end of the current quarter. With this critical catalyst approaching, investors and healthcare stakeholders are taking a closer look at this innovative company poised to disrupt the $10 billion surgical site infection (SSI) market.
A Formidable Challenge in Modern Surgery
Despite significant advances in surgical techniques and prophylactic measures, surgical site infections remain one of healthcare’s most persistent and costly problems. Up to 30% of patients undergoing colorectal surgeries develop infections, leading to extended hospital stays (7-11 additional days), substantially increased healthcare costs ($25,000+ per infection), and alarmingly, up to an 11-fold increase in mortality risk.
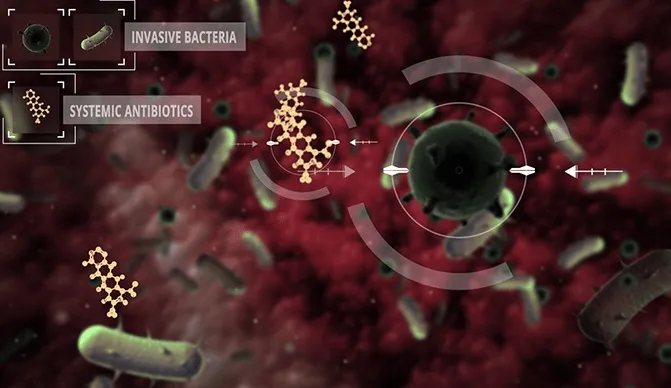
The current standard of care—primarily systemic antibiotics administered shortly before surgery—leaves a critical protection gap. While these antibiotics circulate in the bloodstream for hours, the infection risk window extends to 30 days post-surgery, with compromised blood flow to the surgical site further limiting antibiotic penetration exactly where it’s needed most.
PolyPid’s Revolutionary Solution: D-PLEX100
PolyPid’s lead product candidate, D-PLEX100, addresses this protection gap through an elegant yet powerful approach. The company’s proprietary PLEX (Polymer-Lipid Encapsulation matriX) technology creates a multi-layered matrix that physically embeds the broad-spectrum antibiotic doxycycline between thousands of alternating polymer and lipid layers.
When applied directly to the surgical site, D-PLEX100 gradually releases the antibiotic over 30 days—precisely matching the infection risk window—delivering continuous, localized protection exactly where it’s needed. This approach achieves 10-115 times higher local antibiotic concentrations while using significantly lower total drug amounts compared to systemic administration, potentially reducing side effects and antibiotic resistance concerns.
Q1 2025 Financial Results and Corporate Update
In its May 14 announcement, PolyPid reported the following financial results for Q1 2025:
- Research and development expenses of $6.1 million (compared to $5.1 million in Q1 2024)
- General and administrative expenses of $1.2 million (compared to $1.0 million in Q1 2024)
- Marketing and business development expenses of $0.3 million (compared to $0.2 million in Q1 2024)
- Net loss of $8.3 million, or ($0.70) per share (compared to $6.4 million, or ($1.37) per share in Q1 2024)
- Cash position of $8.0 million as of March 31, 2025 (compared to $15.6 million on December 31, 2024)
More important than the financials, however, is the corporate update provided by the company. PolyPid successfully completed enrollment of 800 patients in the SHIELD II Phase 3 trial, a major achievement that followed the independent Data Safety Monitoring Board’s recommendation to conclude the study at the lowest sample size reassessment option—a signal many analysts interpret as potentially positive for the trial’s outcome.
CEO Dikla Czaczkes Akselbrad emphasized the company’s confidence: “PolyPid is on track for a transformational year in 2025. We continue to view the SHIELD II Phase 3 trial as a derisked study. This assessment has been further strengthened by the 800-patient sample size reassessment which helps ensure the study has sufficient power to conclusively confirm D-PLEX100’s treatment benefit and we believe this increases the trial’s overall probability of success.”
The company also outlined its strategic roadmap, including:
- Advancing regulatory submission preparations for planned 2026 filings with the FDA and EMA
- Progressing commercial launch preparations
- Continuing partnership discussions with multiple potential U.S. partners
- Potential additional funding of $27.0 million through warrant exercises upon positive Phase 3 results
Compelling Clinical Evidence and Trial Progress
The SHIELD II trial’s completion of enrollment represents a significant milestone for PolyPid. This pivotal study follows encouraging results seen in earlier trials:
- In Phase 2 trials, D-PLEX100 demonstrated a 59% reduction in the combined endpoint of surgical site infections and mortality.
- In the SHIELD I Phase 3 trial’s pre-specified subgroup analysis of patients with large surgical incisions (>20cm), D-PLEX100 reduced the primary endpoint (SSIs, reinterventions, and mortality) by a significant 54% (p=0.0032).
The independent Data Safety Monitoring Board’s recommendation to conclude SHIELD II at 800 patients—the lowest sample size reassessment option after reviewing unblinded interim data from 430 patients—is viewed by many analysts as a potentially positive signal for the trial’s ultimate outcome. This recommendation came after the DSMB had options to recommend stopping for futility, continuing as originally planned, or increasing the sample size to as many as 1,100 patients.
Regulatory Advantages and Commercial Strategy
The FDA has already recognized D-PLEX100’s potential with three key designations:
- Breakthrough Therapy Designation
- Fast Track Status
- Qualified Infectious Disease Product (QIDP) Designation
These designations could accelerate the regulatory review process and provide extended market exclusivity, potentially giving PolyPid a stronger competitive position upon approval. In its Q1 update, the company confirmed plans to leverage these designations for NDA submission in early 2026, with a European MAA to follow.
The commercial opportunity is substantial, with approximately 12 million relevant surgical procedures performed annually in the U.S. and another 8 million in Europe. PolyPid has already secured a European commercialization partnership with Advanz Pharma worth up to $115 million plus double-digit royalties.
According to the company’s Q1 update, active partnership discussions are ongoing with multiple potential U.S. partners. This dual-track approach—preparing for independent commercialization while exploring partnership opportunities—gives PolyPid flexibility to maximize D-PLEX100’s market potential.
Beyond Surgical Infections: The Broader PLEX Platform
While the company’s Q1 update focused primarily on the D-PLEX100 program, PolyPid’s PLEX technology platform has broader applications that represent additional long-term value drivers. The company is advancing OncoPLEX, which applies the same controlled-release concept to deliver chemotherapy directly to tumors, potentially revolutionizing treatment for solid cancers including glioblastoma.
In December 2024, PolyPid announced a collaboration with ImmunoGenesis to develop novel formulations combining PLEX technology with ImmunoGenesis’ STING agonist for enhanced cancer immunotherapy—further validating the platform’s versatility. This expansion beyond surgical applications demonstrates the scalability of PolyPid’s core technology.
Financial Position and Funding Strategy
As detailed in the Q1 2025 report, PolyPid had $8.0 million in cash and cash equivalents as of March 31, 2025, compared to $15.6 million at the end of 2024. Management states this will fund operations into Q3 2025, covering the crucial SHIELD II data readout period.
A significant aspect of PolyPid’s financial strategy involves warrant potential. Upon announcement of positive SHIELD II results, warrants from the company’s December 2024 financing would be eligible for exercise, potentially generating an additional $27.0 million. Management emphasized in the Q1 update that this additional funding could extend PolyPid’s runway beyond anticipated NDA approval, positioning the company for a strong negotiating position in partnership discussions.
Wall Street analysts maintain a bullish outlook on PolyPid, with an average price target of $12.33 according to TipRanks—representing over 300% upside from current trading levels around $2.90. Analysts from JMP Securities, H.C. Wainwright, and Craig-Hallum have all reiterated Buy ratings with price targets ranging from $10-14.
The Road Ahead: Key Takeaways from the Q1 Update
With top-line SHIELD II results expected within weeks, PolyPid’s Q1 update paints the picture of a company methodically preparing for a potential breakthrough. As CEO Dikla Czaczkes Akselbrad emphasized during the announcement: “PolyPid is on track for a transformational year in 2025. We continue to view the SHIELD II Phase 3 trial as a derisked study… we believe this increases the trial’s overall probability of success.”
The Q1 update outlined a clear roadmap for the coming months:
- Near-term Catalyst: Top-line SHIELD II results expected by the end of Q2 2025
- Regulatory Path: NDA submission planned for early 2026, leveraging Fast Track and Breakthrough Therapy designations
- Commercial Preparation: Dual-track approach of internal preparations alongside partnership discussions
- Financial Strategy: Current funding through data readout with potential for substantial warrant exercise proceeds upon positive results
If successful, D-PLEX100 would represent the first major innovation in surgical infection prevention in decades, addressing a critical unmet need while potentially saving healthcare systems billions annually. For investors watching this space, PolyPid’s Q1 update reinforces the company’s positioning at the intersection of innovative technology, significant unmet medical need, and a clear path to commercialization.
As the company prepares for what could be the most significant quarter in its history, PolyPid exemplifies how targeted innovation can address longstanding healthcare challenges while creating substantial value for patients, healthcare systems, and investors alike.
* Paid Advertisement: This content is a paid advertisement. Wall Street Wire has received compensation from PolyPid Ltd for promotional media services provided on an ongoing subscription basis. This content is for informational purposes only and does not constitute financial advice. Wall Street Wire is not a broker-dealer or investment adviser. Full compensation details and information regarding the operator of Wall Street Wire are available redditwire.com/terms. We are not responsible for any price targets that may be cited in this article nor do we endorse them, they are quoted based on publicly available news reports and additional price targets may exist that may not have been quoted. Readers are advised to refer to the full reports mentioned on various systems and the disclaimers/disclosures they may be subject to.
The Block Brief
Get the next story before the market does.
Startup funding, venture capital and under-the-radar companies, in your inbox. Free.